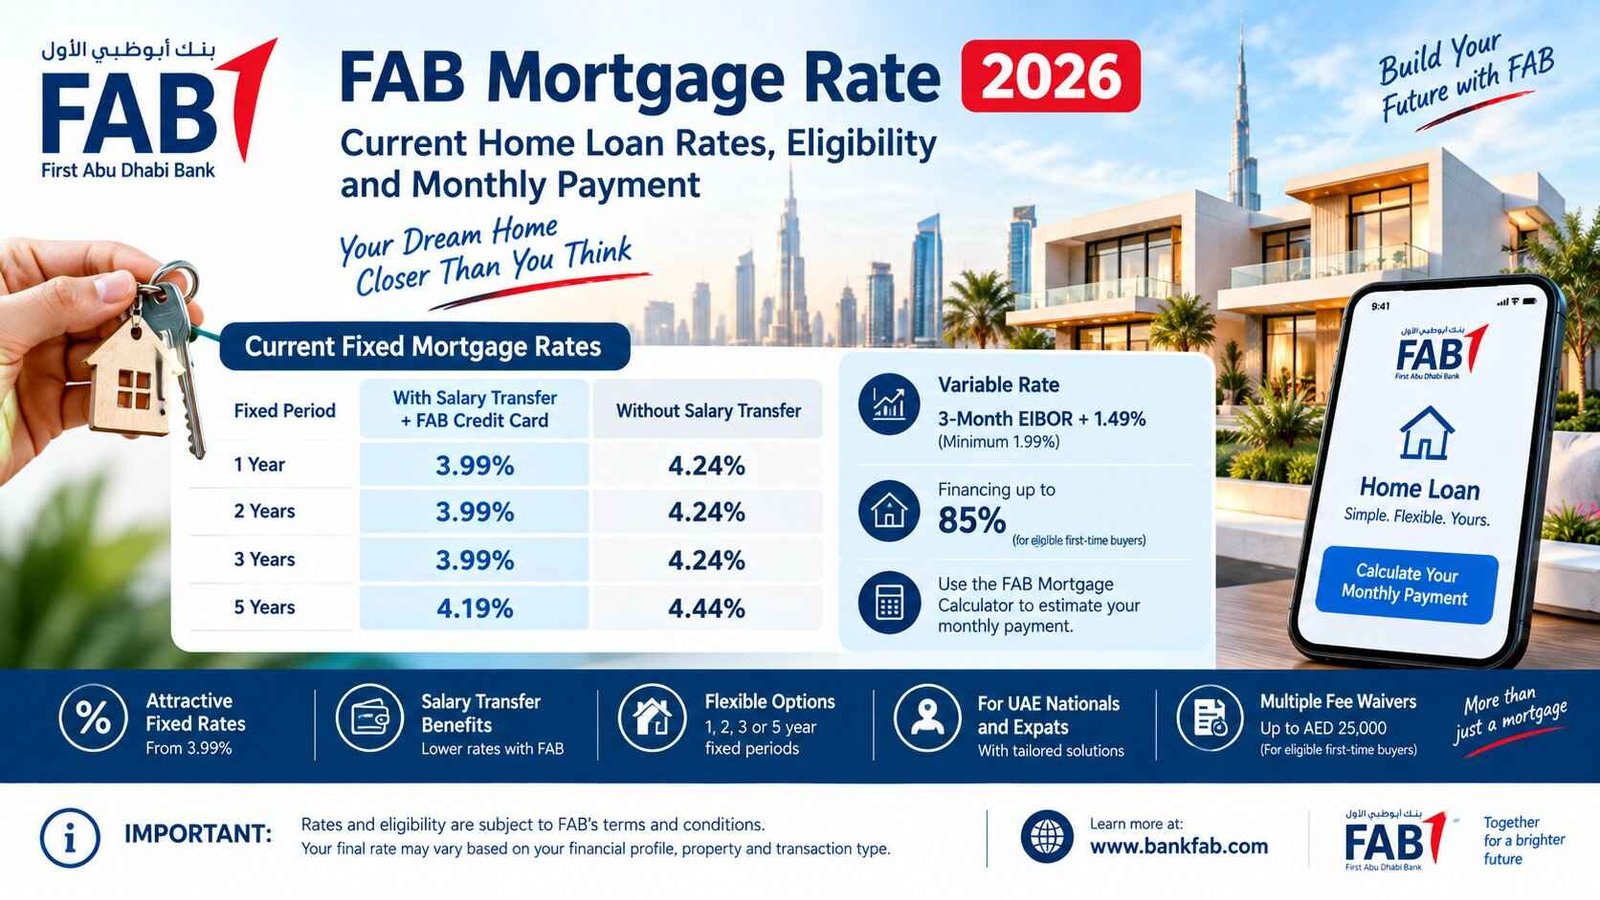
FAB Mortgage Rate 2026: Current Home Loan Rates, Eligibility and Monthly Payment
If you are looking for a home in the UAE and have started checking mortgage rates, you have probably noticed one thing: the rate you see in an advertisement is not always the rate you will actually get.
That is why people searching for the FAB mortgage rate usually want more than just one percentage. They want to know how much FAB charges, whether the rate changes with salary transfer, how long the fixed rate lasts, how much they may need for a down payment, and what the monthly payment could look like.
FAB currently advertises fixed mortgage rates starting from 3.99% for eligible new mortgage customers. The published rate depends on the fixed period and whether you transfer your salary to FAB and take a FAB credit card.
So, before looking at a property and calculating a monthly payment, it is worth understanding what that 3.99% actually means.
Safety Note: A mortgage is a long-term financial commitment. This article is for general information only and does not guarantee mortgage approval or a particular interest rate. Your final FAB offer can depend on your income, existing commitments, property, credit profile and other eligibility conditions. Always check the latest official FAB mortgage terms before applying. For more UAE banking guides and balance-check information, visit the UAEBankBalance.com .
What Is the FAB Mortgage Rate in 2026?
For FAB’s current home loan offer, the advertised fixed rates start at 3.99%.
For fresh mortgage customers, FAB currently publishes the following fixed-rate options:
| Fixed period | Salary transfer + FAB Credit Card | Without salary transfer |
|---|---|---|
| 1 year | 3.99% | 4.24% |
| 2 years | 3.99% | 4.24% |
| 3 years | 3.99% | 4.24% |
| 5 years | 4.19% | 4.44% |
These are FAB’s currently published rates and are subject to the applicable conditions. The 3.99% headline rate therefore does not mean every borrower will automatically receive 3.99%.
FAB also states that the published rates apply to fresh mortgage customers. Existing FAB mortgage customers can have different pricing based on their existing mortgage contract and terms.
Why Does FAB Show Different Mortgage Rates?
This is where many home buyers get confused.
You may see a FAB mortgage advertisement showing 3.99%, then discover another rate when checking the offer. There is a simple reason: FAB has different pricing depending on the arrangement.
The lowest published fixed rate is linked to customers who transfer their salary to a FAB account and choose a FAB credit card.
Customers who do not transfer their salary have a higher published rate.
For example, the current three-year fixed rates are:
- 3.99% with salary transfer and FAB credit card
- 4.24% without salary transfer
For a five-year fixed period, the published rates are 4.19% and 4.44%, respectively.
That 0.25 percentage-point difference may look small when you first see it. But on a large mortgage over several years, even a small rate difference can affect your repayment.
This is why you should compare the complete mortgage offer, not only the headline rate.
FAB Fixed Mortgage Rate Options
One useful thing about the FAB mortgage is that you can choose different fixed-rate periods.
The currently published options are one, two, three and five years.
1-Year Fixed Rate
The current advertised rate is:
3.99% with salary transfer and FAB credit card
or
4.24% without salary transfer.
A shorter fixed period can make sense for someone who expects market rates to change and does not want to lock in a longer period.
However, there is no guarantee that the rate available after the fixed period will be lower.
2-Year Fixed Rate
FAB currently lists:
3.99% with salary transfer and FAB credit card
and
4.24% without salary transfer.
This gives borrowers two years of rate certainty before moving to the applicable subsequent rate.
3-Year Fixed Rate
The three-year option is also currently advertised at:
3.99% with salary transfer and FAB credit card
or
4.24% without salary transfer.
For many buyers, three years can feel like a middle ground between a very short fixed period and locking in for five years.
5-Year Fixed Rate
The five-year fixed rate is currently:
4.19% with salary transfer and FAB credit card
or
4.44% without salary transfer.
The advantage is straightforward: you get longer rate certainty.
The trade-off is that the five-year rate is higher than FAB’s currently advertised one-, two- and three-year rates.
What Happens After the Fixed Rate Ends?
This is one of the most important questions to ask before signing a mortgage.
A fixed rate normally applies only for the agreed fixed period. After that period, the mortgage moves to the applicable variable rate under the mortgage agreement.
For FAB’s current offer, the subsequent rate for customers with salary transfer is linked to 3-month EIBOR + 1.50%, subject to the stated minimum-rate conditions.
This means you should not calculate the entire 20- or 25-year mortgage as though the introductory fixed rate will remain unchanged.
Your payment after the fixed period can be different.
That is why a good mortgage comparison should look at both:
- The initial fixed rate
- The rate that applies afterward
Can You Get a FAB Mortgage With Salary Transfer?
Yes. FAB’s published mortgage pricing specifically includes a lower-rate option for customers who transfer their salary to a FAB account and choose a FAB credit card.
The salary-transfer arrangement can therefore make a difference to your mortgage pricing.
But do not look only at the mortgage rate.
If you are considering transferring your salary, check the complete conditions, including the banking relationship and credit-card requirements, before making your decision.
How Much Can FAB Finance?
The amount you can borrow is not simply based on the property price.
FAB assesses your financial situation and the mortgage transaction before determining how much you may qualify for.
FAB currently states that eligible first-time buyers can receive financing of up to 85% under the applicable conditions.
That does not mean every applicant will automatically receive 85% financing.
Your actual financing percentage can depend on factors such as the property, applicant profile, transaction type and applicable lending requirements.
This is an important point if you are saving for a property in Dubai or Abu Dhabi.
You should not assume that having enough money for a small down payment automatically means FAB will approve the rest.
FAB Mortgage Calculator: How to Estimate Your Monthly Payment
If you already know the approximate property price, the easiest way to start is with the official FAB mortgage calculator.
FAB’s calculator allows you to enter information such as:
- Property price
- Down payment
- Mortgage period
- Annual interest rate
It then provides an estimated mortgage amount and monthly repayment. FAB also explains that the calculator is an estimate and that the applicable down payment depends on the transaction type and relevant conditions.
FAB Mortgage Calculator
Estimate your monthly mortgage payment based on the property price, down payment, interest rate and loan period.
Calculator Disclaimer: This calculator provides an estimated monthly mortgage payment for information purposes only. It does not represent a FAB mortgage offer or guarantee eligibility, approval, interest rate, or financing amount. Actual payments and terms may vary based on the lender's assessment and applicable conditions.
Example of How to Think About the Calculation
Imagine you are considering a property priced at AED 1,500,000.
If you have AED 300,000 available for the down payment, the remaining amount you are considering financing would be:
AED 1,200,000
You could then enter the property price, down payment, mortgage period and applicable interest rate into the FAB calculator.
The resulting monthly payment is only an illustration. Your actual FAB mortgage repayment can be different because the final rate, financing amount, fees and other conditions depend on your approved application.
This is much safer than assuming that a headline 3.99% rate tells you exactly what your monthly payment will be.
FAB Mortgage Eligibility
FAB does not determine mortgage eligibility from one factor alone.
Your application can involve your income, expenses, existing financial commitments, employment situation, credit profile, property and other requirements.
FAB's mortgage process begins with submitting your interest, followed by a consultation with a mortgage specialist. Once you have an idea of your budget, FAB says you can also apply for an Approval in Principle (AIP) to get an estimate of how much you may be eligible to borrow.
This can be particularly useful before committing to a property.
Instead of choosing a property first and then discovering that the required mortgage is too high, an AIP can help you understand your approximate borrowing capacity beforehand.
What Documents May Be Required?
The exact documents depend on your situation and mortgage product.
FAB's application process includes documentation after the property valuation stage. The bank may require financial and property-related documents before the mortgage can proceed.
For this reason, it is better not to rely on a generic online checklist.
Your documents can differ depending on whether you are:
- A UAE national
- An expatriate resident
- A salaried employee
- Self-employed
- Buying a completed property
- Buying an investment property
- Transferring an existing mortgage
FAB can confirm the documents applicable to your particular application.
FAB Mortgage Application Process
The process is easier to understand when you break it into stages.
Step 1: Check Your Budget
Before applying, work out how much you can realistically afford each month.
Do not use your maximum possible borrowing amount as your target property budget.
Leave room for service charges, insurance, maintenance, utilities and other homeownership costs.
Step 2: Use the FAB Mortgage Calculator
Enter your estimated property price, down payment, mortgage period and annual rate.
This gives you an initial idea of the monthly repayment.
Step 3: Submit Your Interest
FAB allows potential customers to start the mortgage journey online or through its mortgage specialists.
Step 4: Discuss Your Eligibility
A FAB mortgage specialist can discuss your situation and the available mortgage options.
This is where you can clarify the rate, salary-transfer conditions, financing amount and other costs.
Step 5: Get Approval in Principle
An AIP can help you understand approximately how much you may be able to borrow before you commit to a property.
It is not the same as final mortgage approval.
Step 6: Property Valuation
After you find a property, FAB's process includes arranging a valuation.
You may also need to sign the relevant property documentation, such as an MOU where applicable.
Step 7: Complete Documentation and Disbursement
After the required checks and documentation are completed, the mortgage moves toward registration and disbursement.
The final process can vary depending on the property and transaction.
FAB Mortgage Fees and Offers
The mortgage rate is only one part of the cost.
FAB currently advertises a processing-fee offer for eligible first-time buyers and customers making handover payments to developers. The bank says the saving can be up to AED 25,000, with the offer stated as valid until 30 September 2026, subject to the published conditions.
FAB also lists other benefits for certain customers, including partial settlement of up to 25% of the outstanding loan annually without fees during the variable-rate period, subject to the applicable terms.
Do not assume every borrower qualifies for every fee waiver.
Always check the conditions attached to the specific offer you are being given.
FAB Mortgage for Expats
FAB also offers mortgage solutions for UAE expatriates.
For residents buying property in the UAE, FAB publishes fixed-rate home loan options and states that expatriates can receive a 60-day grace period before the first instalment for new mortgages under the applicable offer.
FAB also offers mortgage products for non-UAE residents buying investment property in the UAE. Its non-resident mortgage page states that financing can be available up to AED 10 million and that the product offers variable-rate options linked to EIBOR or MBR, subject to conditions.
So if you live outside the UAE but want to buy UAE property, do not automatically compare yourself with a UAE-resident mortgage applicant.
The product and eligibility conditions can be different.
FAB Islamic Home Finance Rates
If you prefer Sharia-compliant financing, FAB Islamic also publishes home finance options.
The current FAB Islamic Home Finance page lists fixed profit rates starting from 3.99%.
Its published fixed profit rates are currently:
| Fixed profit period | Salary transfer + FAB Islamic Credit Card | Without salary transfer |
|---|---|---|
| 1 year | 3.99% | 4.24% |
| 2 years | 3.99% | 4.24% |
| 3 years | 3.99% | 4.24% |
| 5 years | 4.19% | 4.44% |
FAB Islamic states that these profit rates apply to new home finance customers, while existing customers can have different rates according to their contracts and terms.
This is worth knowing if you search for FAB mortgage rate but actually want Islamic home finance rather than conventional mortgage financing.
FAB Mortgage Rate vs Monthly Payment
A lower rate does not automatically mean a better mortgage for every person.
For example, imagine two offers have similar loan amounts but one has a lower initial rate and the other offers a longer fixed period.
The first option could produce a lower payment initially.
The second could provide more certainty if you are worried about future rate changes.
The right question is therefore not simply:
“Which bank has the lowest mortgage rate?”
A better question is:
“Which mortgage gives me a payment I can comfortably afford and terms that still work when the fixed period ends?”
That is the approach you should take when comparing FAB with other UAE banks.
What to Check Before Applying for a FAB Mortgage
Before signing anything, check these points carefully:
- Your exact fixed interest or profit rate
- How long the fixed period lasts
- The rate that applies after the fixed period
- Whether salary transfer is required
- Whether a FAB credit card is required for the advertised rate
- Minimum down payment
- Maximum financing amount
- Processing fees
- Valuation fees
- Insurance requirements
- Early settlement conditions
- Partial settlement rules
- Property eligibility
- Monthly repayment
- Total cost over the mortgage period
The headline rate is only one part of the deal.
People Also Ask About FAB Mortgage Rate
What is the lowest FAB mortgage rate in 2026?
FAB currently advertises fixed mortgage rates starting from 3.99% for eligible fresh mortgage customers. The rate depends on the applicable conditions, including the fixed period and salary-transfer arrangement.
Is 3.99% available without salary transfer?
FAB's current published table shows 4.24% for the one-, two- and three-year fixed options without salary transfer, compared with 3.99% when salary is transferred to FAB and the customer takes a FAB credit card.
What is the FAB 5-year mortgage rate?
The currently published five-year fixed rate is 4.19% with salary transfer and a FAB credit card, or 4.44% without salary transfer, subject to the applicable terms.
Does FAB offer a mortgage calculator?
Yes. FAB provides an official mortgage calculator where you can enter the property price, down payment, mortgage period and annual interest rate to estimate your mortgage amount and monthly repayment.
Can expats get a FAB mortgage in the UAE?
Yes. FAB offers home loan options for UAE residents, including expatriates. It also has separate mortgage products for non-UAE residents buying investment property in the UAE. Eligibility and financing conditions differ by applicant and property.
Final Takeaway
If you are searching for the FAB mortgage rate, the number to remember right now is 3.99%, but do not stop there.
That is the starting fixed rate advertised by FAB for eligible fresh mortgage customers under the applicable conditions. The current published rates range from 3.99% to 4.44% depending on the fixed period and whether salary is transferred to FAB with the required credit-card arrangement.
The smarter way to compare the mortgage is to look at the whole picture: your down payment, monthly repayment, fixed period, rate after the fixed period, fees and your ability to comfortably manage the payment for years.
If you are already considering a specific property, use the official FAB mortgage calculator first, then ask FAB for the exact offer based on your own financial profile.