How to Check Your AECB Credit Score Online in the UAE (2026): Step-by-Step, Fees, the New 3i Score and How to Improve It
Your credit score is one of the most important numbers in your financial life in the UAE. Banks check it before approving a credit card, personal loan or mortgage, and some landlords and service providers now ask for it too. The good news: checking your own score online takes about five minutes and costs very little. The less obvious news: the way the score works changed at the end of October 2026, and most guides online have not caught up. This guide covers how to check your score step by step, what it costs, what the new 3i score means, and how to improve it.
SAFETY NOTE: uaebankbalance.com is only an informational platform. We are not the Etihad Credit Bureau (AECB), a bank, a credit repair company or a licensed financial adviser, and nothing on this page is financial advice. Fees, features and score ranges can change, so confirm everything on the official site. To check your score or report, use only the official Etihad Credit Bureau website: etihadbureau.ae or its official app from the Apple App Store or Google Play. For official consumer protection rules, see the Central Bank of the UAE: centralbank.ae. Never enter your card details or Emirates ID on a lookalike site, and never pay anyone who promises to “repair” or “boost” your credit score for a fee.
Quick Answer: How to Check Your AECB Credit Score Online
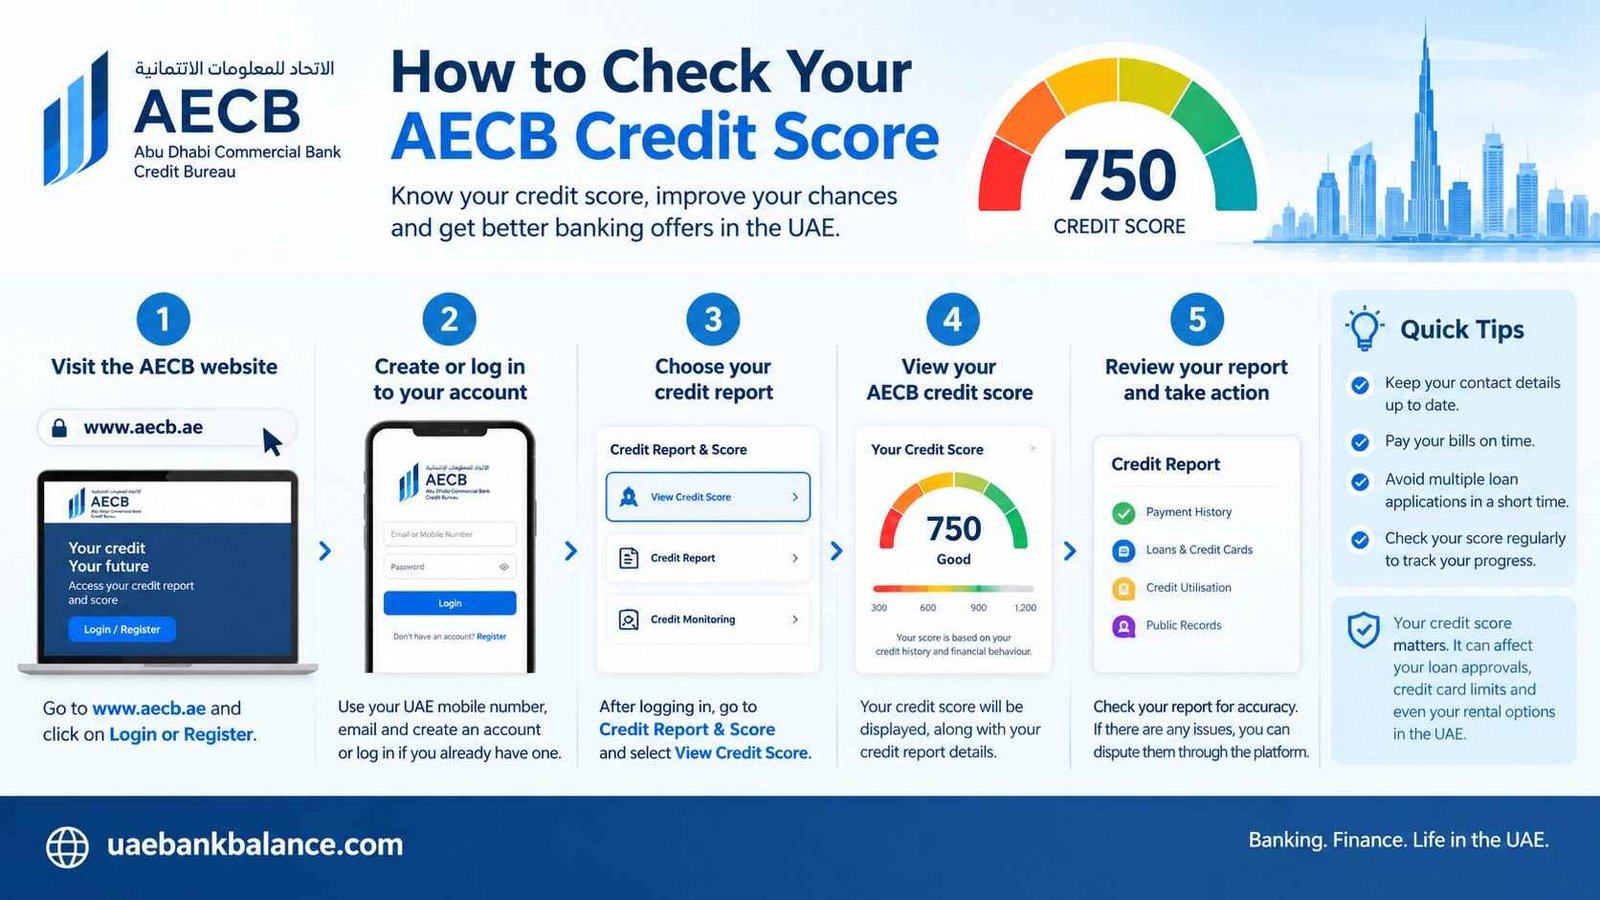
- Go to etihadbureau.ae or open the official Etihad Credit Bureau app.
- Log in with UAE Pass.
- Choose Credit Score (score only) or Credit Report (full report with the score).
- Pay the fee online.
- Download the PDF instantly.
| Item | Details |
|---|---|
| Official channels | Etihad Credit Bureau website and mobile app |
| Login | UAE Pass |
| Score only | Reported at AED 10.50 including VAT |
| Full credit report (includes score) | Reported at AED 84 including VAT |
| Delivery | Instant PDF |
| New score range | 300 to 850 (established credit) or 300 to 650 (limited credit history) under Credit Score 3i |
Big Update: Credit Score 3i Has Changed the Rules
Etihad Credit Bureau has launched Credit Score 3i, its third-generation model, introduced at its new Abu Dhabi office. Here is what is different, based on the bureau’s announcements:
| Old model | Credit Score 3i | |
|---|---|---|
| Range | 300 to 900 | 300 to 850 for people with established credit, 300 to 650 for people who are new to credit or new to the UAE |
| Credit behaviour reviewed | 24 months | 36 months |
| Recovery after defaults | Slower | The bureau says improvements can be reflected within six months after defaults are settled, depending on your later behaviour |
| Explanation | Limited | The report shows positive and negative factors behind your score, with tips |
| Coverage | People with established credit files | Also eligible people with limited credit history |
What this means for you:
- Your score may look different from before. A new range does not mean you suddenly became riskier.
- If you have a New-to-Credit score, it is capped at 650 by design. Do not compare it with the 850 scale.
- Old score tables are out of date. Many websites still publish bands built for the 300 to 900 scale. Do not rely on them for the new model.
- The rollout may be gradual, so check your own report to see which model you are on.
How to Check Your AECB Credit Score Online: Step by Step
Method 1: Through the website
- Open etihadbureau.ae in your browser. Type the address yourself rather than clicking an ad.
- Select Log in and choose UAE Pass.
- Confirm your identity in the UAE Pass app.
- Choose Credit Score or Credit Report.
- Pay the fee online with your card.
- Download the PDF. It is also stored under your purchase history.
Method 2: Through the Etihad Credit Bureau app
- Download the official app from the Apple App Store or Google Play. Check the publisher name is Etihad Credit Bureau.
- Log in with UAE Pass (or register with your Emirates ID, mobile number and email, if prompted).
- Select the score or report, pay in the app, and view or download it.
Other routes
- Government apps: some guides say you can also reach the service through apps like TAMM or DubaiNow after signing in with UAE Pass. Availability can change, so use them only if they show the official Etihad Credit Bureau service.
- Bank apps: some banks reportedly show a score inside their own apps. Features and fees vary, and a bank may display its own version, so confirm what you are seeing.
- Walk-in: the bureau has opened a new walk-in office in Abu Dhabi. Check its website for services and opening hours before visiting.
What you need
- A valid Emirates ID
- UAE Pass set up and verified on your phone
- The mobile number and email linked to your records
- A debit or credit card for the fee
Score or Full Report: Which Should You Buy?
| Option | Best for |
|---|---|
| Score only (about AED 10.50) | A quick check before applying for a card or loan |
| Full credit report (about AED 84) | Spotting errors, seeing every account and late payment, preparing for a mortgage or large loan |
If you are preparing a loan or mortgage application, or you think something is wrong, the full report is worth the extra cost, because the score alone does not show you why it is what it is.
Is There a Free Way to Check?
Honestly, not reliably. Several websites claim you can get a free AECB score, but the dependable route is the official paid product, which is inexpensive. Some banks or promotions may show a score for free, but conditions change. Treat any “100% free forever” offer with suspicion, especially if it asks for your card number, OTP or Emirates ID on an unfamiliar site.
How to Read Your AECB Report
When you open the PDF, look at these sections:
- Personal details. Check your name, Emirates ID, date of birth and contact details are correct.
- Your score and score type. Note whether it is a Mature score (up to 850) or a New-to-Credit score (up to 650).
- Score factors. Under 3i, the report explains what is helping or hurting your score.
- Credit accounts. Every card, loan and facility, with limits, balances and status.
- Payment history. Look for late or missed payments.
- Enquiries. The record of lenders who checked your file.
- Defaults and cheque information, if any.
Tip: compare the accounts listed with what you actually have. Accounts you do not recognise could be a data error or a sign of identity fraud.
What Is a Good AECB Credit Score Now?
Here is where you need to be careful. Until recently, many sites quoted bands for the 300 to 900 scale, and different sites published different bands. For example, one guide treats roughly 700 and above as good, while another lists the good band as starting in the 640s. Those tables do not necessarily apply to the new model.
What we can say responsibly:
- Higher is better, and a higher score signals lower risk to lenders.
- Banks use their own criteria. The score is one input alongside your salary, existing debt, employment and the product you want.
- The bureau does not give you a pass or fail, and a lender may still decline you with a high score or approve you with a lower one.
- Watch your trend and your factors rather than chasing a single number.
As the new model settles, ask your bank what score or band it needs for the product you want, and check whether any official band labels are published on etihadbureau.ae.
What Affects Your Credit Score?
The bureau lists several factors, which include:
- Credit utilisation: how much of your limits you use
- Active credit usage: how you use your accounts over time
- Credit applications: how often you apply for new credit
- Payment behaviour and payment history: whether you pay on time
- Cheque behaviour: bounced cheque history
The model now looks back 36 months. Data comes from banks, finance companies and other reporting providers. Reports have also included Tabby and Tamara buy now, pay later account information since July 2026. One guide notes the bureau has said this does not affect the current score, but treat repayments on these accounts seriously anyway, because lenders can see them.
How to Improve Your AECB Credit Score
- Pay every instalment and card bill on time. Set up automatic payments, and at least cover the minimum.
- Keep your card balances low compared with your limits. Paying in full each month is best.
- Avoid applying for several cards or loans at once. Each application leaves a record.
- Never bounce a cheque. Keep enough funds in the account.
- Clear any defaults or arrears. The bureau says its new model may reflect improvement within six months after defaults are settled, if you then keep up good behaviour.
- Keep older accounts in good standing, and do not open or close accounts without a reason.
- Check for errors and dispute anything wrong (see below).
- Be patient. Scores reflect months of behaviour, not a single payment.
If you recently lost your job or are struggling with payments, read our guide on what to do about bank loans after job loss, and speak to your lender early.
How to Dispute a Wrong Entry
- Download your full credit report and mark the wrong item.
- Contact the bank or lender that reported it first, because they supplied the data. Ask for a written correction or confirmation.
- Raise a dispute through the bureau using its website or app, following its process, and attach your evidence.
- Download your report again after the correction to confirm it has been updated.
Keep copies of all emails, receipts and settlement letters.
Common Problems and Fixes
“I can’t log in with UAE Pass.” Make sure your UAE Pass account is verified at the right level and the app is up to date. If problems continue, contact UAE Pass or the bureau through the official app.
“My score looks different now.” The new 3i model uses a different scale and a longer look-back period. Compare your score type, factors and accounts, not just the number.
“I only have a score up to 650.” You are likely on the New-to-Credit scale. It is capped by design, and it can move as you build a history.
“No score is showing.” You may have too little credit history. Building a record with a small, well-managed credit product can help.
“There is an account I do not recognise.” Contact the lender immediately and the bureau. If you suspect fraud, report it and secure your accounts.
“The payment failed.” Check that your card is enabled for online payments, and try again later or use another card.
Why Your Score Matters for Cards, Loans and Rent
- Credit cards: banks check your score and your income. See our guide to getting a Visa credit card for the other requirements, such as the 50% debt burden rule.
- Personal loans and mortgages: your score influences approval and sometimes pricing.
- Renting: one guide reports that since May 2026 landlords can request a tenant’s score, but only with your UAE Pass consent. Check the official details before relying on this.
- Employers and service providers: some may ask for it in certain situations, always with your consent.
Credit Score Scams to Avoid
- Fake AECB or “Etihad Bureau” websites and apps that look official but collect your card and ID details. Type the address yourself and check the app publisher.
- “Credit repair” agents who promise to delete accurate negative records for a fee. Accurate records cannot simply be erased, and you can dispute genuine errors yourself for free.
- Messages claiming your score is about to drop unless you click a link.
- WhatsApp or social media offers of “instant score boost”.
If you lose money, contact your bank immediately and report the fraud.
Frequently Asked Questions
How do I check my AECB credit score online? Go to etihadbureau.ae or use the official app, log in with UAE Pass, choose Credit Score or Credit Report, pay the fee and download the PDF.
How much does it cost to check my AECB credit score? Sources report about AED 10.50 for the score and about AED 84 for the full report, including VAT. Confirm current fees on the official site.
Can I check my AECB credit score for free? Not reliably. The official score and report are paid, though some banks or promotions may show a score. Beware of sites that claim otherwise.
What is the AECB credit score range now? Under Credit Score 3i it is 300 to 850 for people with established credit and 300 to 650 for people with limited credit history. The older model used 300 to 900.
What is Credit Score 3i? The bureau’s third-generation scoring model. It reviews 36 months of behaviour, includes people with limited history, and explains the factors behind your score.
What is a good AECB credit score? Higher is better, but lenders set their own requirements, and old 300 to 900 band tables may not apply to the new model. Ask your lender what it looks for.
Does checking my own score lower it? Checking your own credit information through the official channel is generally not treated like a lender application, but confirm on the bureau’s site.
How long does it take to improve my score? It depends on your history. The bureau says improvements can be reflected within six months after defaults are settled, if good behaviour continues.
Can I remove a late payment from my report? Only if it is wrong. Accurate records stay for the period the bureau applies. You can dispute errors.
What is the difference between the AECB score and the report? The score is a single number. The report contains your accounts, payment history, enquiries and the factors behind the score.
Do I need UAE Pass to check my score? UAE Pass is the main login. Some flows also allow registration with your Emirates ID, mobile number and email.
Do Tabby and Tamara affect my credit report? They have been included in credit reports since July 2026. One guide says they do not affect the current score, but lenders can see the information.
What if I am new to the UAE with no credit history? You may get a New-to-Credit score, capped at 650, or no score yet. Building a small, well-managed credit history helps.
What score do I need for a credit card or mortgage? There is no single number. Banks look at your score, income, existing debts and their own policy.
Final Thoughts
Checking your AECB score online is fast, cheap and one of the best financial habits you can build in the UAE. Do it before you apply for a card, loan or mortgage, read the factors, fix any errors, and pay on time. And remember that the scoring system itself has just changed, so look at your score type and trend rather than comparing yourself with old charts.
Disclaimer: uaebankbalance.com is an informational platform and is not affiliated with the Etihad Credit Bureau, any bank or any government authority. Information is based on published sources as of 2 November 2026 and may change. It is not financial or legal advice.